
How much will health care cost in retirement? — Useful Finds #15
Hi from Stefan,
Welcome to the fifteenth issue of this biweekly newsletter.
Nothing here is sponsored or written for compensation.
The rising costs of retiree health care
Fidelity’s estimate of retiree lifetime health expenses is up 7.5% from one year ago: “a [single] 65-year-old retiring in 2026 can expect to spend an average of $185,500 on health care and medical expenses throughout retirement”
Is international retirement for you?
A new International Living survey found that 83% of respondents were interested in or actively exploring a retirement that spans two countries—or even three.
I’d be happy spending part of my summer someplace cool, and most of my winter someplace warm, except for a few weeks of skiing.
A weekly unplugging
David Bashevkin writes that The Sabbath Is a Chance to Read Again. Beyond its religious significance for observant Jews, he describes the benefits of spending one day each week disconnected from our devices, reading books and spending time with friends and family.
Answer to a user question
Steve and J.M. both asked how to set up their TIPS ladder today with a delayed start so that it begins payouts some years in the future.
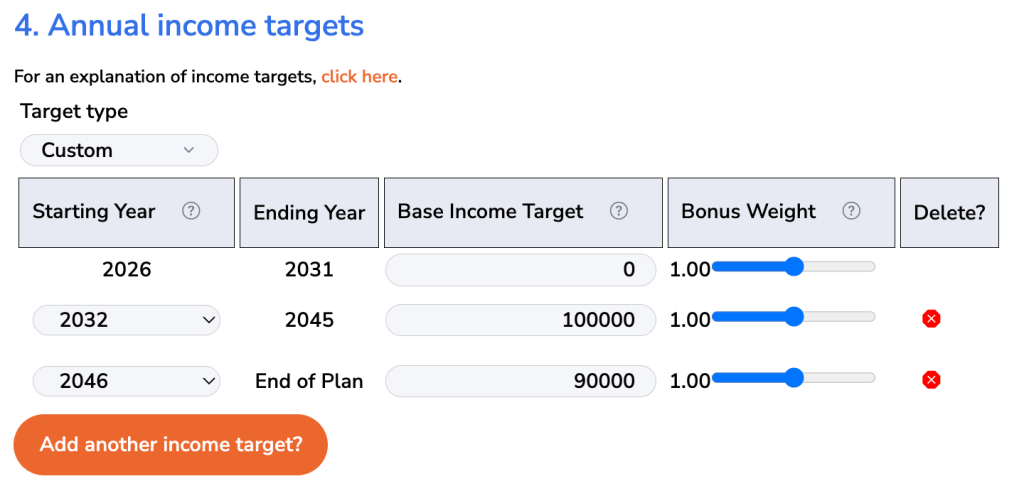
You can do this with a Custom Income Target, which lets you set different base income targets for different time periods.
Suppose you expect earned income through the end of 2031 and don’t need a large withdrawal from TIPS until 2032, but you want to lock in today’s historically above-average TIPS yields.
On the Annual income targets tab, select Custom as the target type.
Click the orange Add another income target? button, then choose 2032 for the starting year.
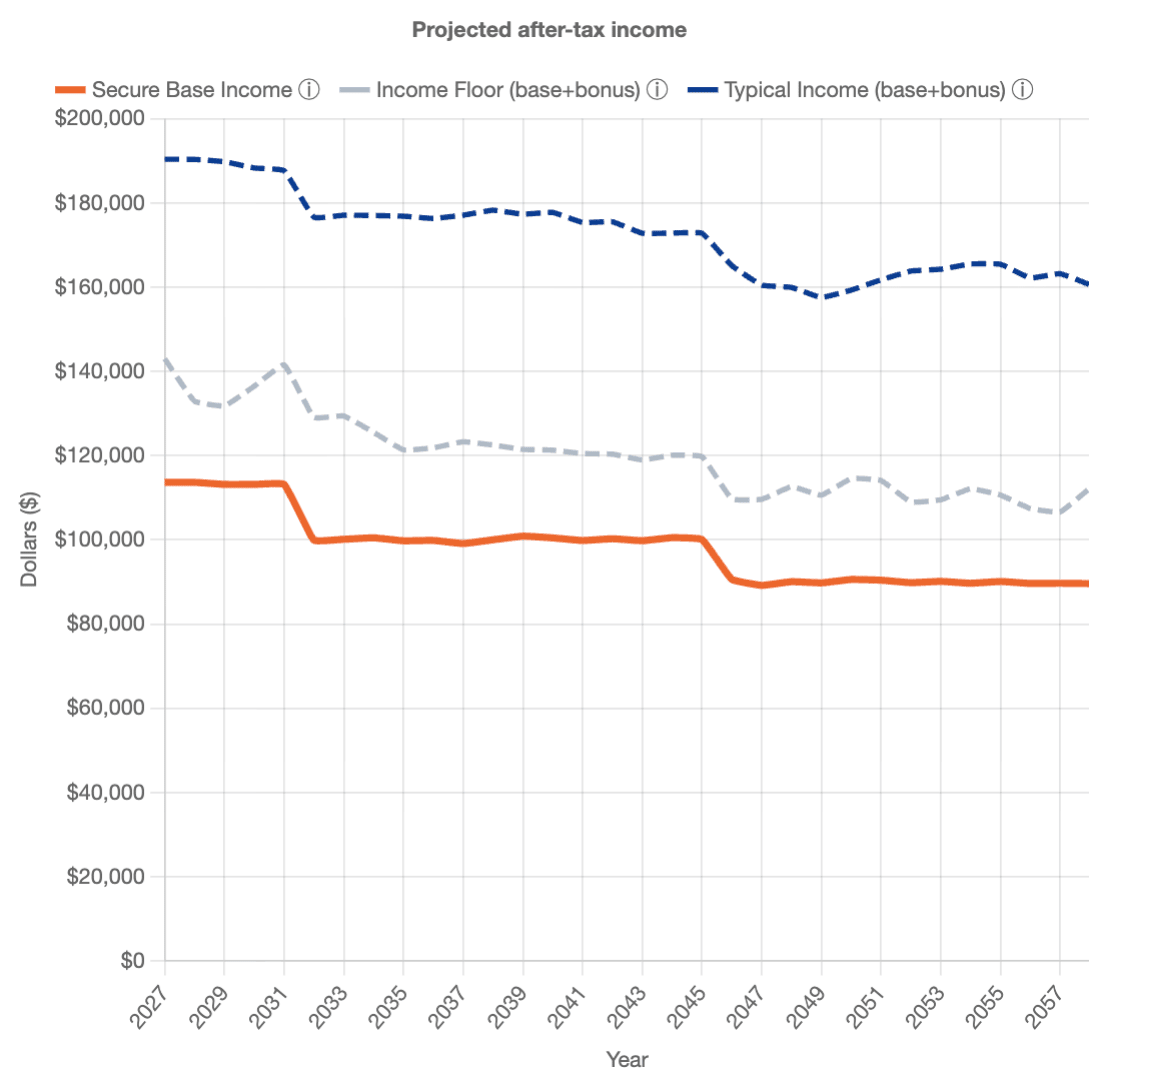
If you set the base income target for 2026-2031, to $0, the model won’t add any TIPS to mature in that time period. You will, however, receive interest income from later maturing TIPS during that time. The first TIPS in your ladder to mature will be in 2032.
In the example shown, the household will make stock withdrawals during 2026-2031.
To avoid stock withdrawals during those years, set the Bonus Weight for that period to 0.0.
The resulting projected income graph looks like this:
Warmly,
Stefan Sharkansky, PhD
Founder of The Best Third