
Can You Afford to Spend More? — Useful Finds #20
Hi from Stefan,
Welcome to the twentieth issue of this biweekly newsletter.
Nothing here is sponsored or written for compensation.
Product tip: Custom Income Targets
Several users have asked how to set time-varying income targets—for example, to use a TIPS ladder solely as a bridge until Social Security begins at 70, to reduce spending at 65 when Medicare kicks in, or to plan for large one-time expenses such as a new car or home remodel.
You can do all of this with The Best Third’s Custom Income Targets.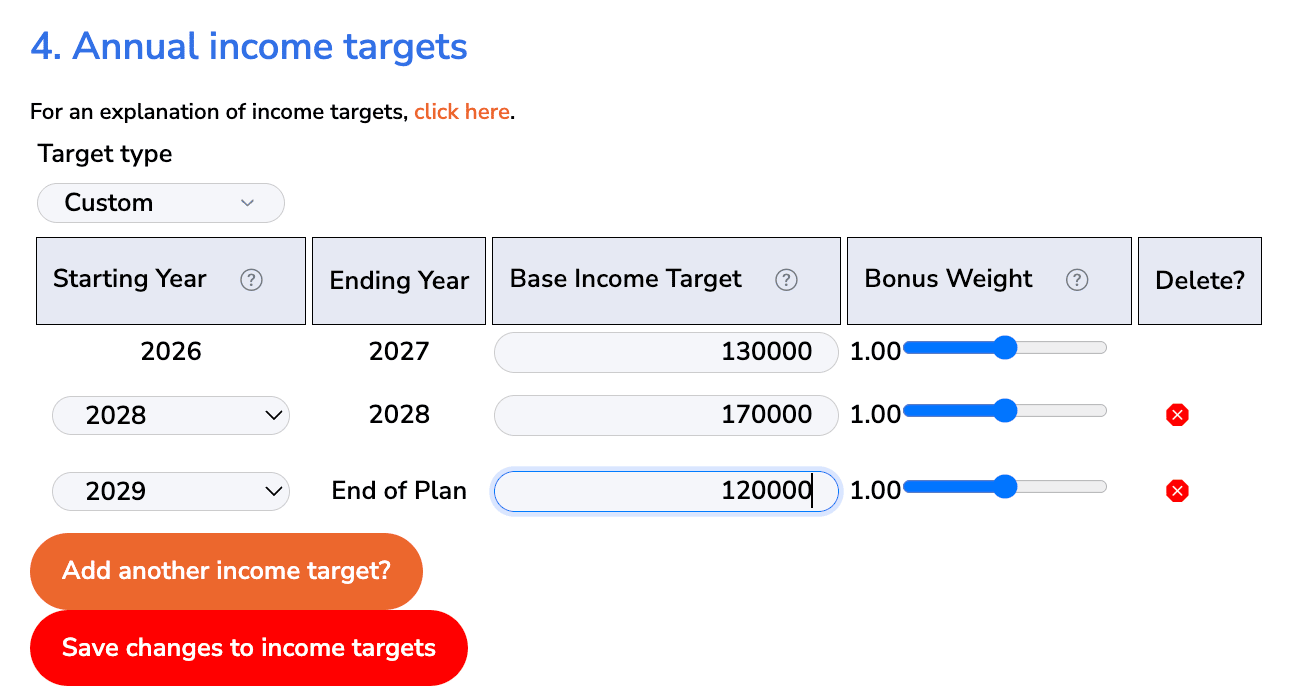
I’m finishing a short instructional video demonstrating how to use this feature. Look for it on The Best Third’s YouTube channel in the next few days.
Four Practical Uses of TIPS in the Portfolio
In Advisor Perspectives Allan Roth continues to beat the drum for TIPS (his words). Among the benefits he discusses is the peace of mind that comes from having a secure, inflation-adjusted income floor, making it easier to spend confidently.
A license to spend
ThinkAdvisor’s article What Still Scares Retired Clients? Spending is about Prudential Financial’s newly released 2026 Retirement Pulse survey.
Among Prudential’s findings about retirement-age households, are that the most common causes of spending hesitation are concerns about inflation, health care costs, the viability of Social Security, and market risk.
More than 60% experience guilt when spending on discretionary items such as big trips and entertainment. At the same time, large numbers express fear of missing out on life.
Prudential’s solution: giving retirees a “license to spend” through guaranteed lifetime income (i.e. the annuities that Prudential sells).
The concerns that underly reluctance to spend are valid, particularly for those who don’t have a well-thought-out plan. Annuities can be a great solution for some.
I realized that the inflation-protected income from TIPS and the additional spending from stocks could give me a more satisfying “license to spend” than the annuities I had considered. Unlike an immediate lifetime annuity, this approach also lets me retain ownership of my assets, providing flexibility if my needs change, and allowing whatever remains to go to my heirs.
The joys of frugal retirement
In the Wall Street Journal, the Retirement Rookies columnists Steve and Karen: How We Inflation-Proofed Our Retirement.
They express enjoyment about their frugal lifestyle, although I sometimes wonder whether they’re more cautious about spending than their financial circumstances require. Of course, there’s nothing wrong with frugality when it’s a preference rather than a necessity.
Their columns are not about the finances of retirement, but delightful and informative essays about how they arrange their lives with the transition away from work, and the ongoing changes with aging.
Warmly,
Stefan Sharkansky, PhD
Founder of The Best Third